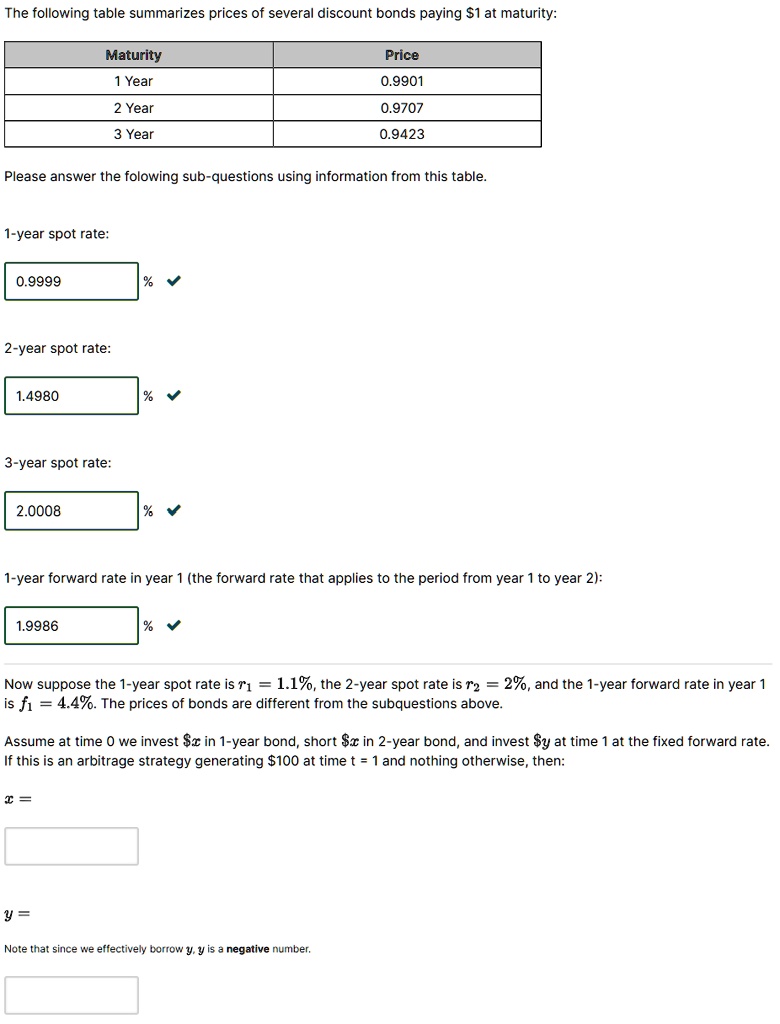
The following table summarizes prices of several discount bonds paying $1 at maturity:
Please answer the folowing sub-questions using information from this table.
1-year spot rate:
%
2-year spot rate:
%
3-year spot rate:
%
1-year forward rate in year 1 (the forward rate that applies to the period from year 1 to year 2):
%
Now suppose the 1-year spot rate is r_(1)=1.1%, the 2-year spot rate is r_(2)=2%, and the 1-year forward rate in year 1
is f_(1)=4.4%. The prices of bonds are different from the subquestions above.
Assume at time 0 we invest $x in 1-year bond, short $x in 2-year bond, and invest $y at time 1 at the fixed forward rate.
If this is an arbitrage strategy generating $100 at time t=1 and nothing otherwise, then:
x=
y=
Note that since we effectively borrow y,y is a negative number.
The following table summarizes prices of several discount bonds paying $1 at maturity
Maturity 1 Year
Price
0.9901
2 Year
0.9707
3 Year
0.9423
Please answer the folowing sub-guestions using information from this table
1-year spot rate:
0.9999
2-year spot rate:
1.4980
3-year spot rate:
2.0008
1-year forward rate in year 1 (the forward rate that applies to the period from year 1 to year 2):
1.9986
Now suppose the 1-year spot rate is =1.1%,the 2-year spot rate is r=2%,and the 1-year forward rate in year1 is fi =4.4%.The prices of bonds are different from the subquestions above
Assume at time O we invest $ in 1-year bond, short $ in 2-year bond, and invest $y at time 1 at the fixed forward rate If this is an arbitrage strategy generating $100 at time t = 1 and nothing otherwise, then:
c=
y =
Note that since we effectively borrow y, y is a negative number.