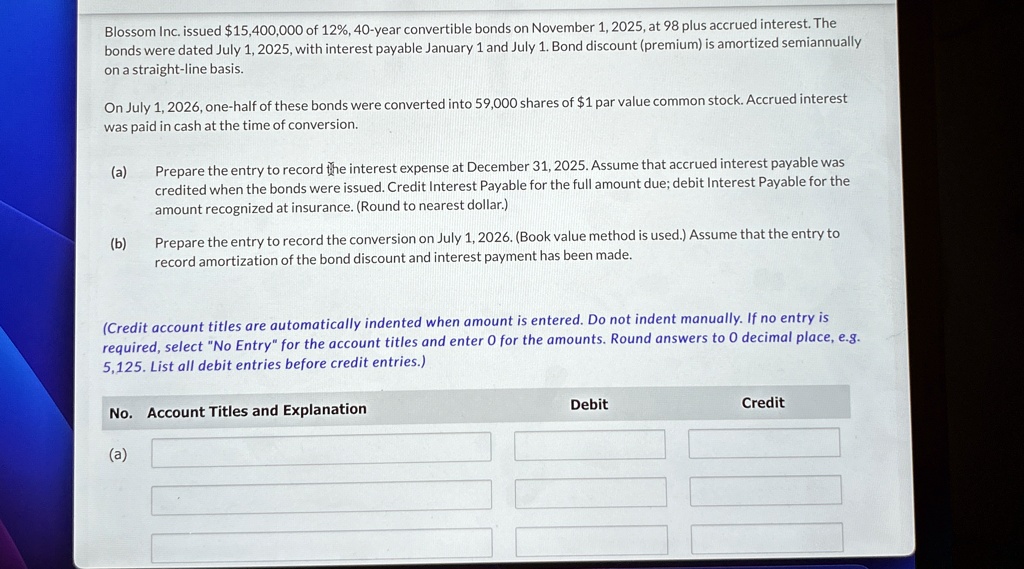
Blossom Inc. issued $15,400,000 of 12%, 40-year convertible bonds on November 1, 2025, at 98 plus accrued interest. The
bonds were dated July 1, 2025, with interest payable January 1 and July 1. Bond discount (premium) is amortized semiannually
on a straight-line basis.
On July 1, 2026, one-half of these bonds were converted into 59,000 shares of $1 par value common stock. Accrued interest
was paid in cash at the time of conversion.
(a)
(b)
Prepare the entry to record the interest expense at December 31, 2025. Assume that accrued interest payable was
credited when the bonds were issued. Credit Interest Payable for the full amount due; debit Interest Payable for the
amount recognized at insurance. (Round to nearest dollar.)
Prepare the entry to record the conversion on July 1, 2026. (Book value method is used.) Assume that the entry to
record amortization of the bond discount and interest payment has been made.
(Credit account titles are automatically indented when amount is entered. Do not indent manually. If no entry is
required, select "No Entry" for the account titles and enter O for the amounts. Round answers to O decimal place, e.g.
5,125. List all debit entries before credit entries.)
No. Account Titles and Explanation
(a)
Debit
Credit