Can I ask that do I answer this question correctly? Do my explaination clear enough? Because I have to present this question in class this week but I don't know whether I do it correctly or not. :(
Problem 5.14. The two-month interest rates in Switzerland and the United States are 2% and 5% per annum, respectively, with continuous compounding. The spot price of the Swiss franc is $0.8000. The futures price for a contract deliverable in two months is $0.8100. What arbitrage opportunities does this create?
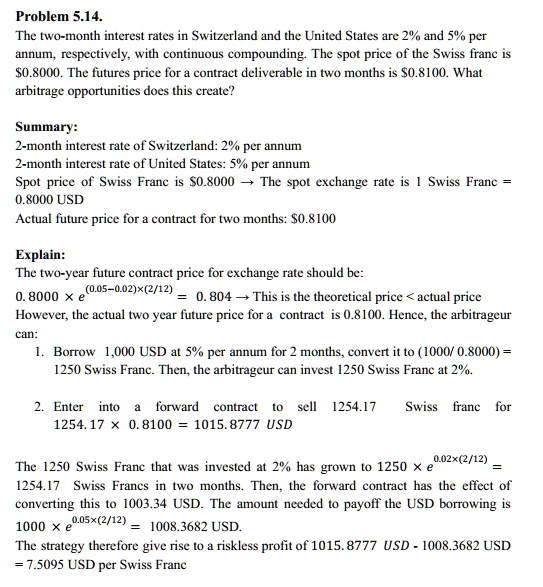
Summary: 2-month interest rate of Switzerland: 2% per annum 2-month interest rate of United States: 5% per annum Spot price of Swiss Franc is $0.8000 The spot exchange rate is 1 Swiss Franc = 0.8000 USD Actual future price for a contract for two months: $0.8100
Explain: The two-year future contract price for exchange rate should be:
However, the actual two year future price for a contract is 0.8100. Hence, the arbitrageur
can: 1. Borrow 1,000 USD at 5% per annum for 2 months, convert it to (1000/ 0.8000)= 1250 Swiss Franc. Then, the arbitrageur can invest 1250 Swiss Franc at 2%
2. Enter into a forward contract to sell 1254.17 1254.170.8100=1015.8777USD
Swiss franc for
The 1250 Swiss Franc that was invested at 2% has grown to 1250 e 1254.17 Swiss Francs in two months. Then, the forward contract has the effect of converting this to 1003.34 USD. The amount needed to payoff the USD borrowing is
The strategy therefore give rise to a riskless profit of 1015.8777 USD - 1008.3682 USD = 7.5095 USD per Swiss Franc