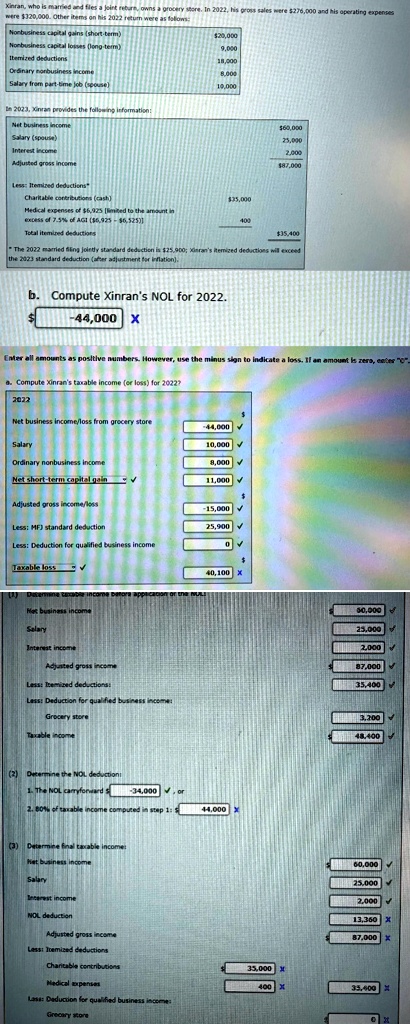
Xinran, who is married and files a joint return, owns a grocery store. In 2022, his gross sales were $276,000 and his operating expenses were $320,000. Other items on his 2022 return were as follows:
Nonbusiness capital gains (short-term)
$20,000
Nonbusiness capital losses (long-term)
9,000
Itemized deductions
18,000
Ordinary nonbusiness income
8,000
Salary from part-time job (spouse)
10,000
In 2023, Xinran provides the following information:
Net business income
$60,000
Salary (spouse)
25,000
Interest income
2,000
Adjusted gross income
$87,000
Less: Itemized deductions*
Charitable contributions (cash)
$35,000
Medical expenses of $6,925 - limited to the amount in
excess of 7.5% of AGI ($6,925 - $6,525)
400
Total itemized deductions
$35,400
* The 2022 married filing jointly standard deduction is $25,900. Xinran's itemized deductions will exceed the 2022 standard deduction (after adjustment for inflation).
b. Compute Xinran's NOL for 2022.
$ -44,000 X
Enter all amounts as positive numbers. However, use the minus sign to indicate a loss. If an amount is zero, enter "0".
a. Compute Xinran's taxable income (or loss) for 2022?
2022
Net business income/loss from grocery store
$ -44,000 ✓
Salary
10,000 ✓
Ordinary nonbusiness income
8,000 ✓
Net short-term capital gain
11,000 ✓
Adjusted gross income/loss
$ -15,000 ✓
Less: MFJ standard deduction
25,900 ✓
Less: Deduction for qualified business income
0 ✓
Taxable loss
$ 40,100 X
(1) Determine taxable income before application of the NOL
Net business income
$ 60,000 ✓
Salary
25,000 ✓
Interest income
2,000 ✓
Adjusted gross income
$ 87,000 ✓
Less: Itemized deductions:
Less: Deduction for qualified business income:
Grocery store
Taxable income
$ 3,200 ✓
$ 48,400 ✓
(2) Determine the NOL deduction:
1. The NOL carryforward $ -34,000 ✓ or
2. 80% of taxable income computed in step 1: $ 44,000 X
(3) Determine final taxable income:
Net business income
$ 60,000 ✓
Salary
25,000 ✓
Interest income
2,000 ✓
NOL deduction
$ 13,360 X
Adjusted gross income
$ 87,000 X
Less: Itemized deductions
Charitable contributions
$ 35,000 X
Medical expenses
400 X
Less: Deduction for qualified business income:
Grocery store
$ 33,600 X