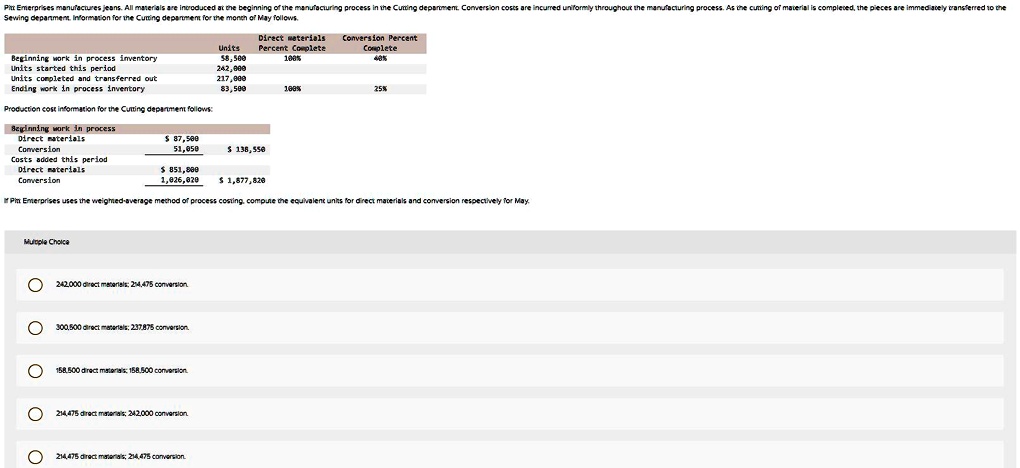
Pitt Enterprises manufactures jeans. All materials are introduced at the beginning of the manufacturing process in the Cutting department. Conversion costs are incurred uniformly throughout the manufacturing process. As the cutting of material is completed, the pieces are immediately transferred to the Sewing department. Information for the Cutting department for the month of May follows.
Units Direct materials Percent Complete Conversion Percent Complete
Beginning work in process inventory 58,500 100% 40%
Units started this period 242,000
Units completed and transferred out 217,000
Ending work in process inventory 83,500 100% 25%
Production cost information for the Cutting department follows:
Beginning work in process
Direct materials $ 87,500 $ 138,550
Conversion 51,050
Costs added this period
Direct materials $ 851,800 $ 1,877,820
Conversion 1,026,020
If Pitt Enterprises uses the weighted-average method of process costing, compute the equivalent units for direct materials and conversion respectively for May.
Multiple Choice
$\circ$ 242,000 direct materials; 214,475 conversion.
$\circ$ 300,500 direct materials; 237,875 conversion.
$\circ$ 158,500 direct materials; 158,500 conversion.
$\circ$ 214,475 direct materials; 242,000 conversion.
$\circ$ 214,475 direct materials; 214,475 conversion.