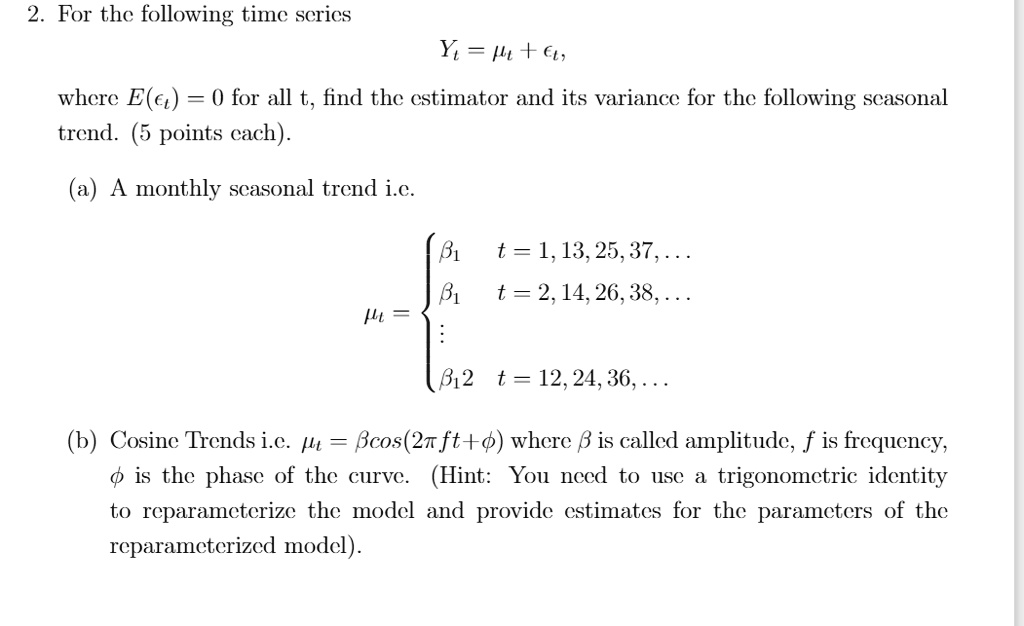
2. For the following time series
$Y_t = \mu_t + \epsilon_t$,
where $E(\epsilon_t) = 0$ for all t, find the estimator and its variance for the following seasonal
trend. (5 points each).
(a) A monthly seasonal trend i.e.
$\mu_t = \begin{cases} \beta_1 & t = 1, 13, 25, 37, ... \\ \beta_1 & t = 2, 14, 26, 38, ... \\ \vdots \\ \beta_{12} & t = 12, 24, 36, ... \end{cases}$
(b) Cosine Trends i.e. $\mu_t = \beta cos(2\pi ft + \phi)$ where $\beta$ is called amplitude, f is frequency,
$\phi$ is the phase of the curve. (Hint: You need to use a trigonometric identity
to reparameterize the model and provide estimates for the parameters of the
reparameterized model).