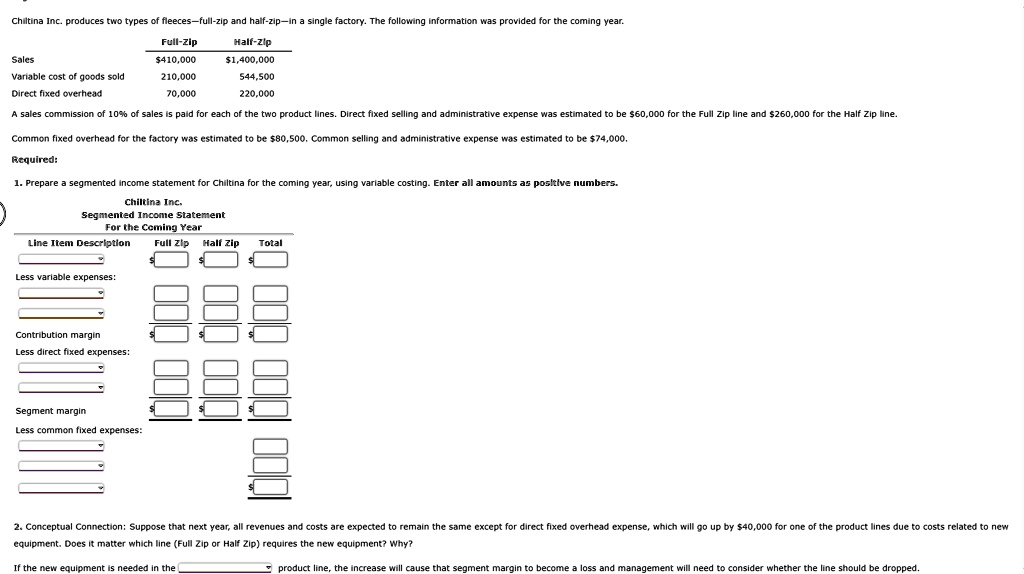
Chiltina Inc. produces two types of fleeces-full-zip and half-zip-in a single factory. The following information was provided for the coming year.
Full-Zip
Half-Zip
Sales
$410,000
$1,400,000
Variable cost of goods sold
210,000
544,500
Direct fixed overhead
70,000
220,000
A sales commission of 10% of sales is paid for each of the two product lines. Direct fixed selling and administrative expense was estimated to be $60,000 for the Full Zip line and $260,000 for the Half Zip line.
Common fixed overhead for the factory was estimated to be $80,500. Common selling and administrative expense was estimated to be $74,000.
Required:
1. Prepare a segmented income statement for Chiltina for the coming year, using variable costing. Enter all amounts as positive numbers.
Chiltina Inc.
Segmented Income Statement
For the Coming Year
Line Item Description
Full Zip Half Zip
Total
Less variable expenses:
Contribution margin
Less direct fixed expenses:
Segment margin
Less common fixed expenses:
Full Zip Half Zip
Total
2. Conceptual Connection: Suppose that next year, all revenues and costs are expected to remain the same except for direct fixed overhead expense, which will go up by $40,000 for one of the product lines due to costs related to new
equipment. Does it matter which line (Full Zip or Half Zip) requires the new equipment? Why?
If the new equipment is needed in the
product line, the increase will cause that segment margin to become a loss and management will need to consider whether the line should be dropped.