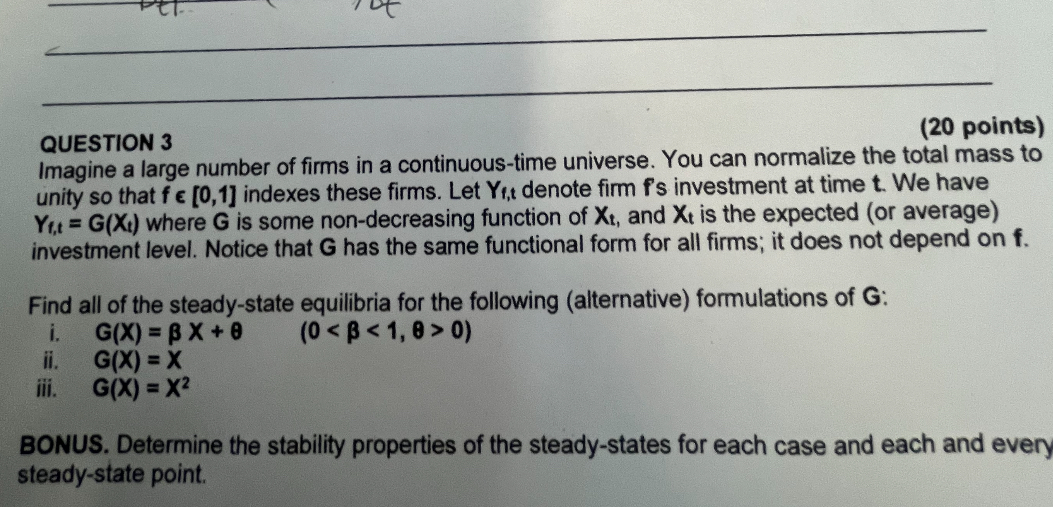
QUESTION 3 (20 points)
Imagine a large number of firms in a continuous-time universe. You can normalize the total mass to unity so that f ? [0,1] indexes these firms. Let Yf,t denote firm f's investment at time t. We have Yf,t = G(Xt) where G is some non-decreasing function of Xt, and Xt is the expected (or average) investment level. Notice that G has the same functional form for all firms; it does not depend on f.
Find all of the steady-state equilibria for the following (alternative) formulations of G:
i. G(X) = ? X + ? (0 < ? < 1, ? > 0)
ii. G(X) = X
iii. G(X) = X²
BONUS. Determine the stability properties of the steady-states for each case and each and every steady-state point.