336 Chapter 7 Accounting Information Systems
Journalize transactions in cash
receipts journal; post to control
account and subsidiary ledger.
(SO 2, 3, 4)
GLS
(a) Balancing totals $38,350
(c) Accounts Receivable $0
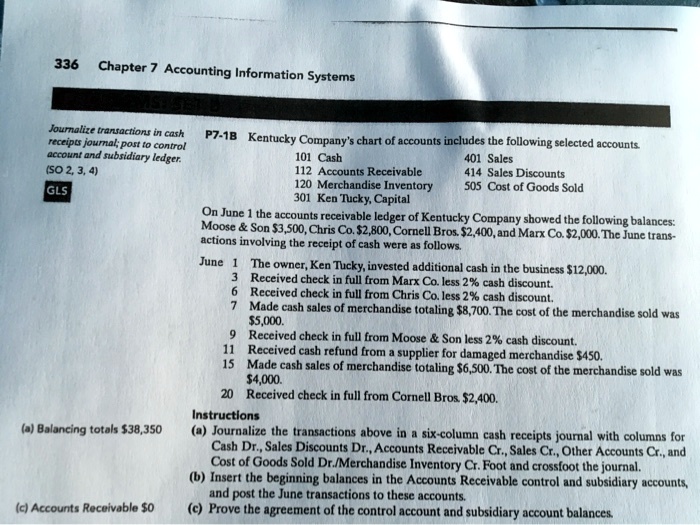
P7-18 Kentucky Company's chart of accounts includes the following selected accounts.
101 Cash
401 Sales
112 Accounts Receivable
414 Sales Discounts
120 Merchandise Inventory
301 Ken Tucky, Capital
505 Cost of Goods Sold
On June 1 the accounts receivable ledger of Kentucky Company showed the following balances:
Moose & Son $3,500, Chris Co. $2,800, Cornell Bros. $2,400, and Marx Co. $2,000. The June trans-
actions involving the receipt of cash were as follows.
June 1 The owner, Ken Tucky, invested additional cash in the business $12,000.
3 Received check in full from Marx Co. less 2% cash discount.
6 Received check in full from Chris Co. less 2% cash discount.
7 Made cash sales of merchandise totaling $8,700. The cost of the merchandise sold was
$5,000.
9 Received check in full from Moose & Son less 2% cash discount.
11 Received cash refund from a supplier for damaged merchandise $450.
15 Made cash sales of merchandise totaling $6,500. The cost of the merchandise sold was
$4,000.
20 Received check in full from Cornell Bros. $2,400.
Instructions
(a) Journalize the transactions above in a six-column cash receipts journal with columns for
Cash Dr., Sales Discounts Dr., Accounts Receivable Cr., Sales Cr., Other Accounts Cr., and
Cost of Goods Sold Dr./Merchandise Inventory Cr. Foot and crossfoot the journal.
(b) Insert the beginning balances in the Accounts Receivable control and subsidiary accounts,
and post the June transactions to these accounts.
(c) Prove the agreement of the control account and subsidiary account balances.