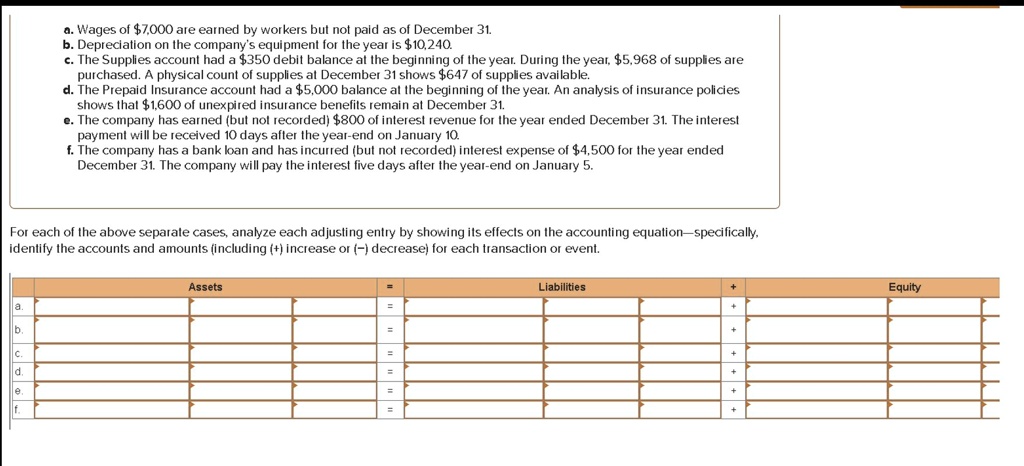
a. Wages of $7,000 are earned by workers but not paid as of December 31.
b. Depreciation on the company's equipment for the year is $10,240.
c. The Supplies account had a $350 debit balance at the beginning of the year. During the year, $5,968 of supplies are
purchased. A physical count of supplies at December 31 shows $647 of supplies available.
d. The Prepaid Insurance account had a $5,000 balance at the beginning of the year. An analysis of insurance policies
shows that $1,600 of unexpired insurance benefits remain at December 31.
e. The company has earned (but not recorded) $800 of interest revenue for the year ended December 31. The interest
payment will be received 10 days after the year-end on January 10.
f. The company has a bank loan and has incurred (but not recorded) interest expense of $4,500 for the year ended
December 31. The company will pay the interest five days after the year-end on January 5.
For each of the above separate cases, analyze each adjusting entry by showing its effects on the accounting equation-specifically,
identify the accounts and amounts (including (+) increase or (-) decrease) for each transaction or event.
Assets
=
=
Liabilities
Equity