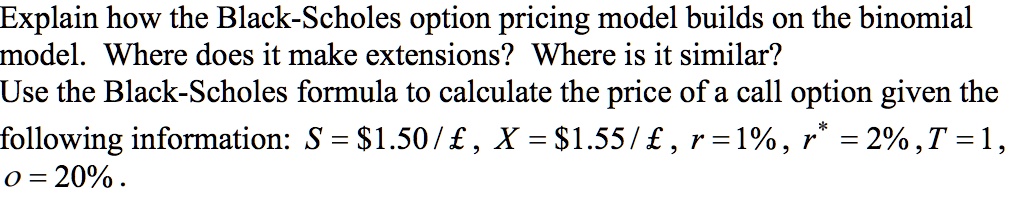
Explain how the Black-Scholes option pricing model builds on the binomial model. Where does it make extensions? Where is it similar? Use the Black-Scholes formula to calculate the price of a call option given the following information: S = $1.50/f, X = $1.55/f, r = 1%, r* = 2%, T = 10, σ = 20%.