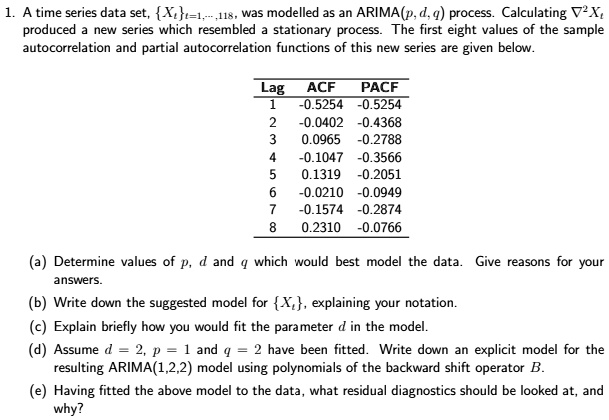
1. A time series data set, \{X_t\}_{t=1,...,118}, was modelled as an ARIMA(p, d, q) process. Calculating \(\nabla^2 X_t\), produced a new series which resembled a stationary process. The first eight values of the sample autocorrelation and partial autocorrelation functions of this new series are given below.
Lag ACF PACF
1 -0.5254 -0.5254
2 -0.0402 -0.4368
3 0.0965 -0.2788
4 -0.1047 -0.3566
5 0.1319 -0.2051
6 -0.0210 -0.0949
7 -0.1574 -0.2874
8 0.2310 -0.0766
(a) Determine values of p, d and q which would best model the data. Give reasons for your answers.
(b) Write down the suggested model for \{X_t\}, explaining your notation.
(c) Explain briefly how you would fit the parameter d in the model.
(d) Assume d = 2, p = 1 and q = 2 have been fitted. Write down an explicit model for the resulting ARIMA(1,2,2) model using polynomials of the backward shift operator B.
(e) Having fitted the above model to the data, what residual diagnostics should be looked at, and why?