Q2
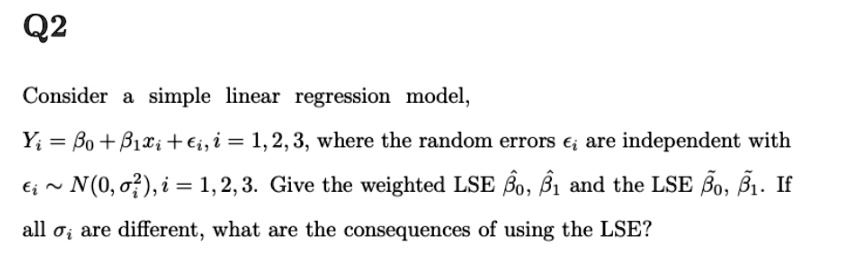
Consider a simple linear regression model,
$Y_i = \beta_0 + \beta_1x_i + \epsilon_i$, $i = 1, 2, 3$, where the random errors $\epsilon_i$ are independent with
$\epsilon_i \sim N(0, \sigma_i^2)$, $i = 1, 2, 3$. Give the weighted LSE $\hat{\beta}_0, \hat{\beta}_1$ and the LSE $\tilde{\beta}_0, \tilde{\beta}_1$. If
all $\sigma_i$ are different, what are the consequences of using the LSE?